Are You Ready to Cast Your Ballot?
California’s General Election is here. Counties have begun mailing ballots and voters can complete and return them as soon as they arrive. The massive CA Voter Information Guide may be a bit overwhelming, but at least we’ve still got several weeks to review them!
To help you understand the most important ballot measure impacting real estate, we’ve provided some detailed information below. I’d like to personally invite you to attend CCAR’s BIG EVENT on Wednesday, October 28th, where you will learn more about Prop 37 and what it means for our business. I also invite you to join us at CCAR’s Appraisal Luncheon Seminar on October 20 to learn about the new appraisal reporting format and practical steps to prepare. Understanding these changes can help you answer clients’ questions and navigate the appraisal process with greater confidence. I encourage you to sign up now to attend, as space is limited.
I look forward to seeing you at our upcoming events this month and encourage you to look for me there! I’d love to get to know you and help you find ways to get the most out of your CCAR membership.
Prop 37 Provides A Path to Homeownership and More New Homes
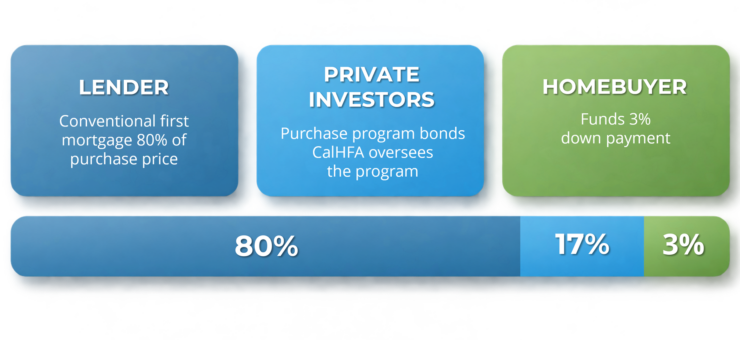
Proposition 37 would authorize $25 billion in privately funded revenue bonds to help eligible Californians buy newly built homes with lower down payments and encourage construction. For REALTORS®, it could expand the pool of qualified buyers and available homes, while buyers would still need to afford monthly payments.
As little as 3% down A low-interest secondary loan could cover up to 17% of the purchase price, combined with a conventional mortgage.
Assistance is a loan Buyers must meet income requirements, make monthly payments, and occupy the home as their residence.
Privately funded, state overseen Private investors would purchase revenue bonds to fund the program, with CalHFA oversight and borrower repayment.
More new homes A fully funded program could support approximately 190,000 homes, depending on investor participation and market conditions.
Prop 37 unlocks homeownership for more middle-class families by making it possible to buy a new home with just 3% down while spurring a wave of new home construction across the state.
NO COST TO TAXPAYERS
Appraisal Reporting Requirements Changing Nov 2, 2026
Effective November 2nd, a new residential appraisal report form (UAD 3.6) reflect major changes in appraisal reports submitted for loans involving Fannie Mae and Freddie Mac. Some lenders are already ordering reports in the new format, so you may encounter these changes before November.
SUMMARY | UAD 3.6 Appraisal Reporting Changes
The new UAD 3.6 format requires more detailed property information, which could mean longer appointments and turnaround times. NAR recommends discussing timing with lenders early, setting realistic client expectations, and documenting improvements, concessions and unusual transaction details clearly in the MLS.
Appraisal Report Changes
One flexible report replaces the familiar fixed forms. The report adapts to the property type and its features, so it may look different from appraisals clients have seen before.
More detailed property information is recorded. Appraisers document features such as individual levels, rooms, improvements, amenities and site characteristics in greater detail.
Photos and supporting information have more defined reporting requirements. The redesigned report specifies which images are required, required with certain circumstances, or optional.
Impact on REALTORS®
Explain the new appearance without treating it as a sign of a problem.
Provide clear facts about improvements, including what was done and when. “Updated kitchen” is less useful than a dated description of work.
Help clients know what to expect at the appointment and respond promptly if an appraiser requests factual information about a property or past sale.
Impact on Buyers/Sellers
Buyers and sellers may receive a less familiar-looking report, but the appraiser’s responsibility to determine value remains the same.
Sellers should be ready to share records of renovations and allow for a potentially longer property visit. More detail does not automatically mean a higher appraisal value.
A visit may involve more documentation than they expect; the homeowner should ask the lender/appraiser about any access or preparation needs for their specific assignment.
CCAR ANNUAL SPONSORS
CCAR is proud to be a RESO Platinum Certified MLS, the highest level of certification available.